A Temporary Federal Program That Helped Limit Premium Increases for Some Medicare Part D Plans Will End After 2026.
If you have a standalone Medicare Part D prescription drug plan, you'll want to pay close attention to the information your plan sent you this fall.
The Centers for Medicare & Medicaid Services (CMS) recently announced that it is ending a temporary program that helped keep premiums more stable for participating Part D drug plans. The program was called the
Medicare Part D Premium Stabilization Demonstration, and it will end after 2026.
What Is Changing?
Medicare made major changes to the Part D prescription drug benefit beginning in 2025. During that transition, CMS created a temporary program to help participating standalone Part D plans manage some of the financial impact and limit large year-to-year premium increases.
For 2026, the program provided participating plans with additional financial assistance and limited how much their total Part D premiums could increase from the previous year.
CMS has now decided that this temporary assistance is no longer needed, so the program will end after 2026, rather than running through 2027 as was originally anticipated. That means Part D plans will set their 2027 premiums without the additional help provided by this temporary program.
Does This Mean My Part D Premium Will Go Up?
Not necessarily.
Ending the program does
not mean everyone's Part D premium will increase. The impact will vary from one plan to another.
To find out whether this change affects you, and by how much, it's important to look at the Part D plans available for 2027 and compare them with your 2026 coverage. Start with the monthly premium, but don't stop there. Changes in deductibles, prescription costs, covered medications and pharmacy networks can all affect what you ultimately pay.
In other words, a higher premium doesn't necessarily mean a plan will cost you more overall, and a lower premium doesn't necessarily mean it will be the least expensive choice for you. What matters is how the plan covers the medications you take and the pharmacies you use.
Although this temporary program is ending, it doesn't mean all federal measures intended to help control Part D premium increases are going away. Other protections remain in place that limit how quickly certain costs used to calculate Part D premiums can rise from year to year.
However, those protections don't put a cap on how much your individual plan's premium can change. That's why it's still important to focus on the details of the plans available to you and compare your 2027 costs and coverage with what you had in 2026.
What Should I Do?
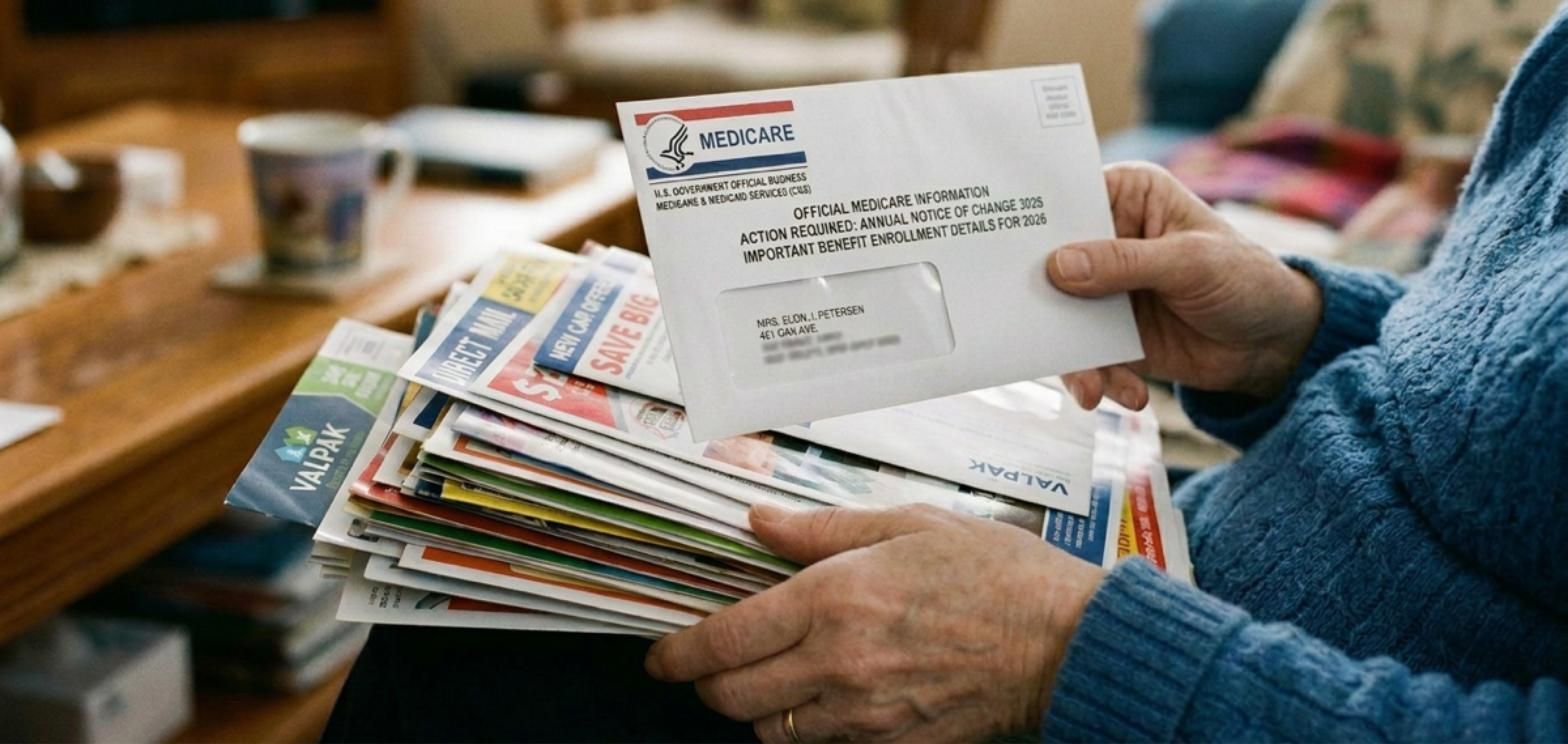
By now, you should have received an
Annual Notice of Change (ANOC) from your current plan, explaining what's changing next year. Review it carefully to see whether your premium, prescription drug coverage, out-of-pocket costs, pharmacy network or other plan features are changing.
As you review it, don't look at the premium alone. A plan with a lower monthly premium could end up costing you more if the medications you take are more expensive under that plan or if the deductible has increased. Likewise, changes to a plan's formulary, deductible or pharmacy network could have a significant impact on your overall costs.
As you review your coverage, consider:
- Are all the prescriptions I take still covered?
- Have my costs (copayments and coinsurance) for those medications changed?
- Is my usual pharmacy still in the plan's network, and is it still considered a preferred pharmacy?
- Has the deductible or monthly premium changed?
- Are there new coverage requirements or restrictions for any of my medications?
- How does my current plan compare with the other Part D options available for 2027?
Medicare Open Enrollment runs from
October 15 through December 7. That's your opportunity to compare your current coverage with other available options for 2027 and make a change if another plan better fits your needs.
You don't have to wait until October 15 to start getting organized, though. When your 2027 plan information arrives, make a list of your current prescriptions, dosages and preferred pharmacies. Having that information ready can make comparing your options much easier.
Conclusion
The end of this temporary Medicare program is good to know about, but there's no reason to assume your prescription drug costs are automatically going to soar. The most important thing you can do is
review your coverage rather than automatically renewing it without looking at the changes.
We are here to help you assess your options and prioritize your needs. Working with a licensed Medicare professional from our team means you don’t have to figure this all out on your own.